Market Position & Competitive Landscape
How School of Rock’s performance-based music education model stacks up in the $5B+ after-school enrichment market.
Market Overview: After-School Enrichment Is a Growth Vertical
The U.S. after-school enrichment market exceeds $5 billion in annual revenue and continues to grow at roughly 5–7% per year, driven by dual-income household demand, increasing parental emphasis on extracurricular development, and a generational shift toward experiential learning over rote academics. Within this broad category, music education occupies a distinct but narrower segment — estimated at $3–4 billion including private lessons, group instruction, and school-based programs — with franchised models representing a small and growing share.
The structural tailwind for enrichment franchises is parental willingness to pay for programs that combine skill development with social engagement. Academic tutoring (Kumon, Mathnasium) dominated the franchise enrichment space for decades, but the competitive landscape has shifted. STEM programs (Code Ninjas, iCode), creative arts, and sports academies have captured a growing share of family spending. The common thread is that parents are buying outcomes — not babysitting — and they are willing to pay premium rates for branded, curriculum-driven programs that deliver measurable progress.
School of Rock sits at an interesting intersection within this market. Music education has historically been fragmented: independent instructors, community music schools, and retail-adjacent models (Music & Arts). The performance-based pedagogy — students learning instruments by rehearsing and performing in bands, culminating in seasonal shows — differentiates the model from traditional lesson-based instruction. It is closer to the “experience economy” than to tutoring, which gives it pricing power but also narrows the addressable market to families specifically seeking music education rather than general enrichment.
That narrower addressable market is the central tension in evaluating the competitive position. A Kumon or Mathnasium franchise serves any family with a school-age child who wants academic improvement — a near-universal need. A School of Rock franchise serves families with children specifically interested in contemporary music performance. The passion-driven nature of the customer base creates strong retention (students who love performing stay enrolled for years), but the top of the funnel is inherently smaller than academic enrichment.
Music vs. Academic Enrichment
Academic tutoring franchises address near-universal parental demand. Music education addresses a passion-driven niche — smaller funnel, but deeper engagement and longer retention cycles once enrolled.
Competitor Comparison
The table below compares School of Rock against direct music education competitors and adjacent enrichment franchises. Investment ranges and fee structures are drawn from publicly available FDD filings.
| Brand | Investment Range | Fee Structure | Unit Count | Revenue Data | Model |
|---|---|---|---|---|---|
| School of Rock | $425K–$705K | 8% royalty + 3% brand fund + up to 3% co-op (up to 14%) | 254 franchised | $672K avg (franchised) | Performance-based music education |
| Bach to Rock | $280K–$640K | 6% royalty + 2% ad fund | ~50 units | Not disclosed | Multi-instrument music school |
| Music & Arts (Guitar Center) | Corporate-owned | N/A (corporate) | ~250 locations | N/A | Retail/lessons hybrid |
| Kumon | $73K–$155K | Variable | 26,000+ worldwide | Not disclosed | Academic tutoring (math & reading) |
| Mathnasium | $113K–$151K | 10% royalty | 1,100+ | Not disclosed | Math tutoring |
| Code Ninjas | $187K–$480K | 8% royalty | 400+ | Not disclosed | STEM/coding education |
Investment ranges from publicly available Franchise Disclosure Documents. Unit counts as of most recent FDD filings. Music & Arts is corporate-owned and not available as a franchise.
Differentiation Analysis: The Performance Model
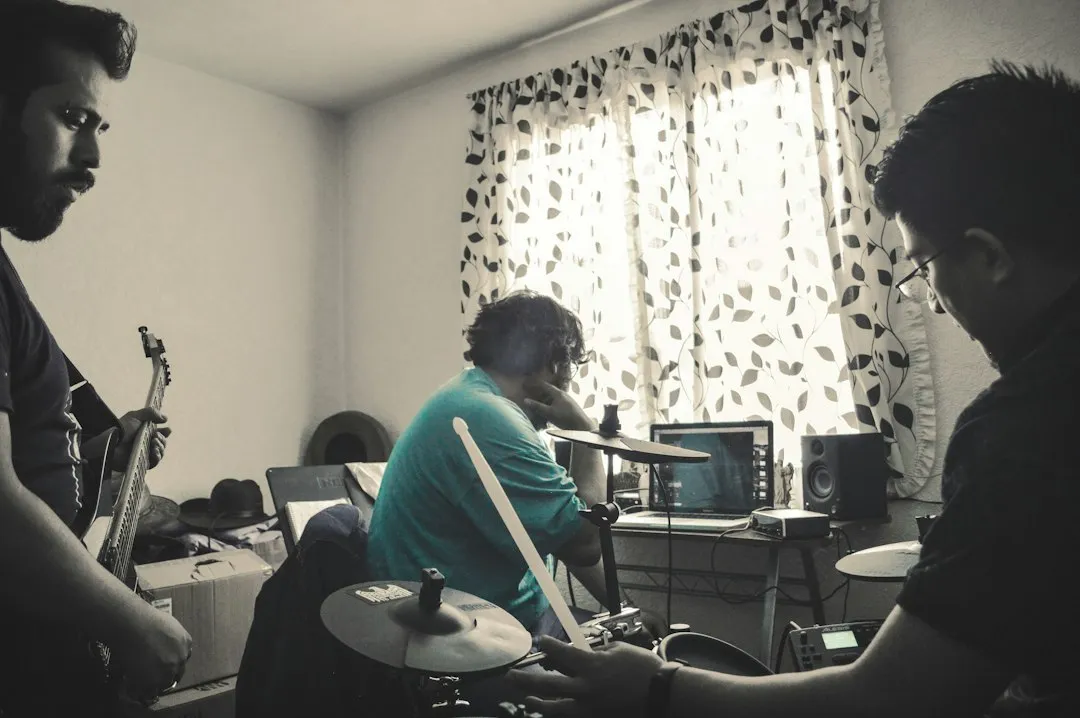
School of Rock’s core differentiator is its performance-based pedagogy. Students do not simply take weekly lessons — they learn by rehearsing in bands with other students and performing live shows each season. This model creates a fundamentally different value proposition from traditional music instruction. The seasonal show cycle (typically four per year) functions as both a pedagogical framework and a marketing engine: parents invite extended family and friends to performances, creating organic referrals that most enrichment franchises cannot replicate.
The “experience economy” angle is genuine and measurable. Retention rates in performance-based programs tend to exceed those of traditional lesson models, because students develop social bonds with bandmates and emotional investment in upcoming shows. A student who drops out of weekly piano lessons loses nothing visible. A student who drops out of a band leaves a gap that peers and instructors notice. That social friction works in the franchisee’s favor — it reduces churn, which is the single most important driver of recurring revenue in enrollment-based businesses.
The vulnerabilities are equally real. The performance model requires a specific kind of instructor: a working or semi-professional musician who can teach, manage a group of children, and commit to a rehearsal schedule. This is a materially different hiring profile from a Kumon tutor or a Mathnasium instructor, and the labor pool is smaller and less predictable. Instructor availability and retention is consistently cited as the primary operational challenge in publicly available franchise owner discussions. The model also requires dedicated rehearsal space with sound isolation, which drives build-out costs higher than a typical tutoring center and limits real estate options.
The addressable market question deserves honest treatment. Academic enrichment franchises can market to any family with a school-age child. Music education franchises market to families with children who want to play contemporary music — a subset of a subset. The passion-driven nature of the enrollment base creates strong unit economics once a location reaches critical mass, but the ramp to that point can be slower and more market-dependent than in academic tutoring. A School of Rock in a music-oriented community with strong school arts programs may draw from a different pool than one in a community where sports dominate extracurricular spending.
Strengths vs. Vulnerabilities
- Strength: Performance model drives retention and organic referrals
- Strength: Emotional engagement creates switching costs
- Vulnerability: Narrow instructor labor pool
- Vulnerability: Addressable market smaller than academic enrichment
- Vulnerability: Sound isolation drives higher build-out costs
Youth Enrichment Brands: The Parent Company Context
School of Rock Franchising LLC is an indirect wholly-owned subsidiary of Youth Enrichment Brands, LLC. This corporate structure matters for prospective franchisees because it determines the strategic priorities, capital allocation decisions, and operational support infrastructure that flow downstream to individual franchise locations.
Multi-brand holding companies in franchising can be a double-edged sword. On the upside, a well-capitalized parent can invest in shared technology platforms, national marketing, and operational best practices that a standalone franchisor might not afford. Cross-brand learnings — enrollment management, instructor scheduling systems, real estate site selection — can benefit all portfolio brands. The downside is the risk of resource dilution: a parent company managing multiple brands may allocate disproportionate attention and investment to whichever brand is growing fastest or generating the highest returns, leaving other brands to operate on legacy systems and stale playbooks.
For a prospective franchisee, the practical question is whether the corporate infrastructure translates into tangible operational support at the unit level. The FDD provides some visibility into this through the training program description, technology platform commitments, and field support staffing. But the most revealing data point may be the gap between company-owned and franchised school performance. Company-owned schools average $925,351 in revenue versus $672,488 for franchised schools — a 38% gap. Some of that difference reflects site selection advantages and market maturity. But it also raises the question of whether the corporate operating playbook is being fully transferred to franchisees, or whether company-owned schools benefit from resources and institutional knowledge that franchisees do not receive.
Dig Into the Numbers
The competitive landscape sets the stage, but the investment decision comes down to the FDD. Read the full financial analysis — Item 7 investment range, Item 19 revenue data, and the fee stack that takes up to 14% off the top.
Read the FDD Analysis →